China Property Signals (#43): The Hong Kong Rebound Moderating (Aug 2026 Data)
About this Newsletter: Get a quick but more granular view of (still) one of the most important sectors in China, with the weekly chart and commentary from Real Estate Foresight (REF) - drawing on 14+ years of REF's research on China housing markets.
The data for August shows the Hong Kong residential rebound is now moderating.
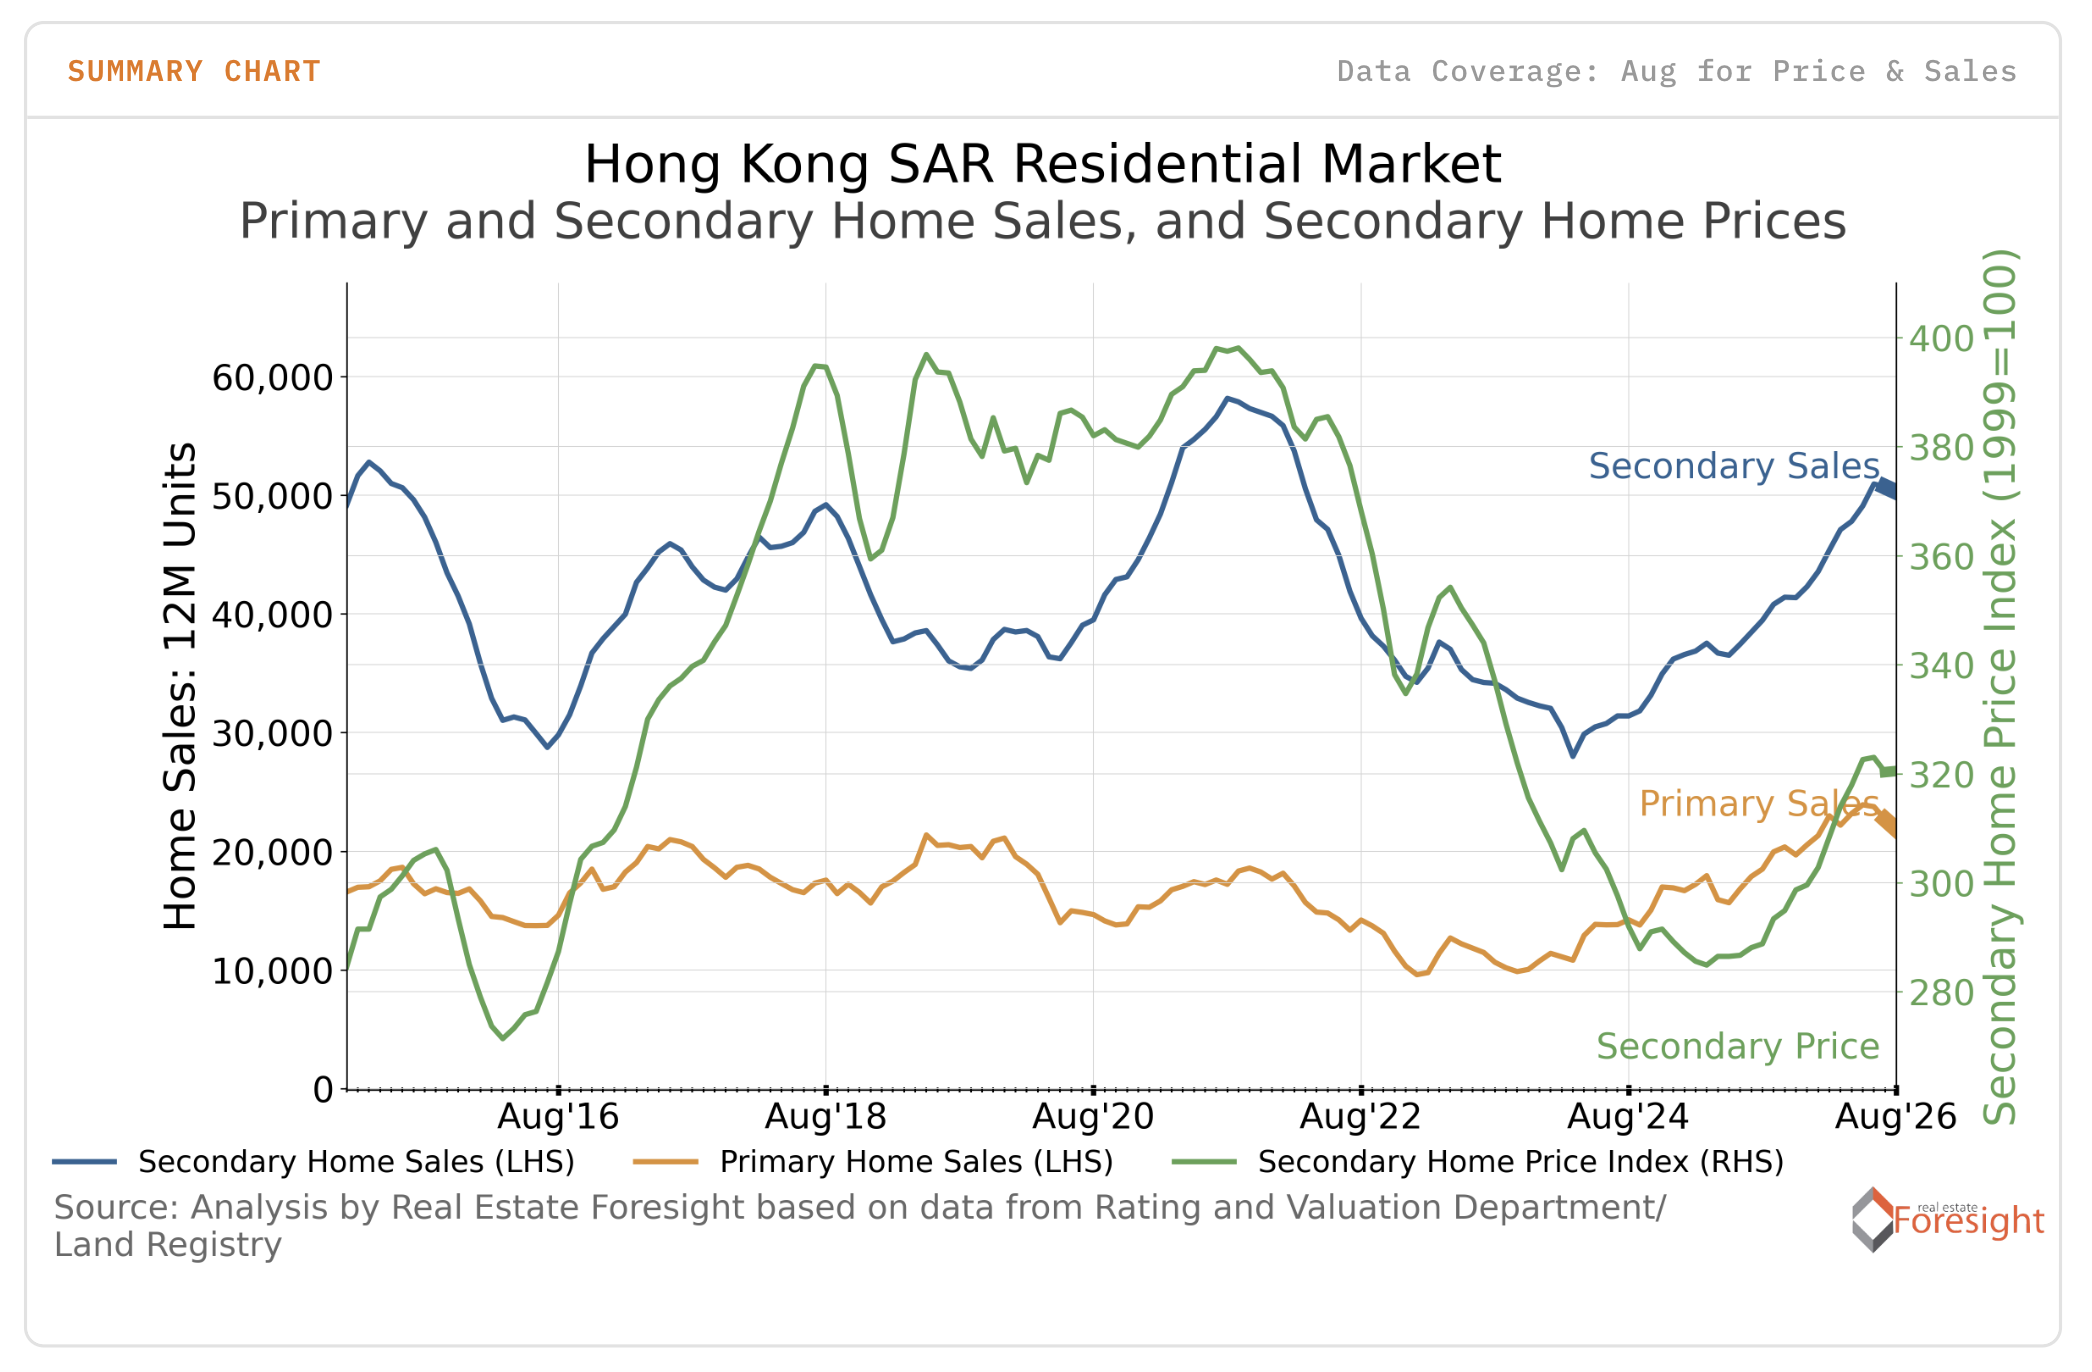
The new home sales growth slowed by 8.8 percentage points to 18.1% y/y, while secondary transactions moderated by 4.5pp to 27.4% y/y. In absolute terms, the 12MMA of new home sales declined to 1,821 units from 1,891 in Jul, broadly in line with the prior cycle peak of 1,818 units reached in Mar 2008. Secondary sales also eased, with the 12MMA declining to 4,189 units from 4,225 in Jul, and remaining well below the historical peak of 10,178 units recorded in Dec 2010.
Prices continued to improve in Aug 2026, although y/y growth moderated slightly. The all-developments index rose 11.0% y/y, with growth slowing by 0.2 percentage points from Jul 2026, while the select developments measure was stronger at +12.3% y/y. This leaves the all-developments index still 19.5% below its Sep 2021 peak, while remaining well above its Mar 2025 trough. The current index level is roughly back to late-2023 levels and close to where it stood in early 2017.
See our Hong Kong Residential Dashboard for more coverage of Hong Kong. Currently in open-access pilot.